


What is the tradeoff between interest and liquidity? This is one of the most fundamental questions in finance, and if you are running a forex brokerage or planning to launch one, the answer affects almost every part of your business.
From the swap rates you charge your clients to the way central bank decisions move your trading volume, the relationship between interest and liquidity sits at the core of how financial markets function.
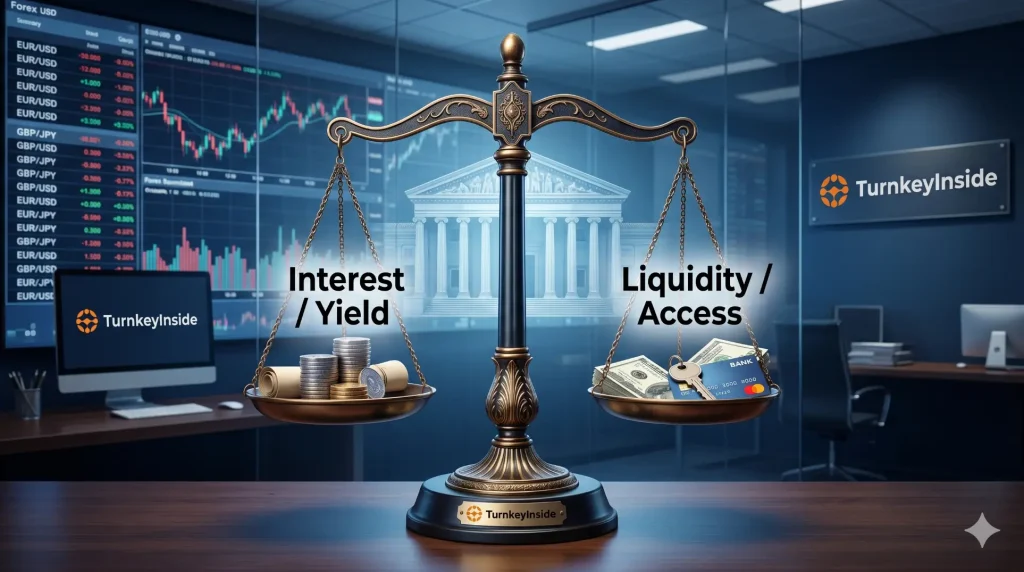
The basic principle is straightforward: the higher the interest rate or yield an asset offers, the less liquid it tends to be. Investors demand higher returns as compensation for locking up their capital in assets that are harder to sell quickly.
Conversely, highly liquid assets like cash or short-term government bonds offer lower returns precisely because they can be converted to cash instantly with minimal risk.
Read More: Liquidity Provision: Everything You Need to Know
Understanding the Interest and Liquidity Tradeoff
What Is the Tradeoff Between Interest and Liquidity – The tradeoff between interest and liquidity is rooted in a simple economic reality: people prefer to have their money available. Holding cash gives you maximum flexibility.
You can spend it, invest it, or move it at any time. But cash earns little to no return. The moment you commit that cash to a longer-term investment, like a bond, a fixed deposit, or a less liquid financial instrument, you give up that flexibility in exchange for a higher yield.
This is what economists call the liquidity premium. The extra return that investors demand for holding less liquid assets is compensation for the risk that they might need their money before the investment matures, and that selling early could mean accepting a lower price or paying a penalty.
In the context of financial markets, this tradeoff shows up everywhere. Short-term Treasury bills yield less than long-term Treasury bonds.
Savings accounts pay less than certificates of deposit. Highly traded major forex pairs have tighter spreads (lower cost) than illiquid exotic pairs. Blue-chip stocks are easier to sell than micro-cap stocks, so investors accept lower expected returns for the liquidity benefit.
For brokerage operators, the practical takeaway is this: the instruments you offer, the way you price them, and the way you manage your own capital all reflect this fundamental tradeoff.
Liquidity Preference Theory and Why It Matters for Brokers
The formal framework for understanding the tradeoff between interest and liquidity comes from John Maynard Keynes’ Liquidity Preference Theory, developed in the 1930s. Keynes argued that interest rates are determined by the supply and demand for money, and that people hold money for three reasons:
1. The transaction motive
What Is the Tradeoff Between Interest and Liquidity – People need cash for everyday purchases and business operations.
For a brokerage, this is your operational capital, the money you need to pay staff, cover LP margin requirements, process client withdrawals, and handle day-to-day expenses.
2. The precautionary motive
What Is the Tradeoff Between Interest and Liquidity – People keep a cash reserve for unexpected expenses or emergencies. For a brokerage, this is your buffer against sudden market events, LP margin calls, or a spike in client withdrawal requests.
Brokers who keep too little precautionary liquidity can find themselves in a cash crunch during volatile markets.
3. The speculative motive
What Is the Tradeoff Between Interest and Liquidity – People hold cash because they expect better investment opportunities in the future. In the brokerage context, this relates to how your clients behave.
When interest rates are low and expected to rise, traders may hold cash and wait. When rates are high, they may deploy capital into carry trades or yield-bearing instruments.
How Interest Rates Drive Forex Market Liquidity
What Is the Tradeoff Between Interest and Liquidity – Interest rates are the single most powerful driver of forex market activity. When central banks change their benchmark rates, or even signal that a change is coming, it triggers massive flows of capital across currencies. These flows create the liquidity that your brokerage depends on.
Consider what happens when the US Federal Reserve raises interest rates. Higher US rates make dollar-denominated assets more attractive to global investors. Capital flows into the United States, demand for USD increases, and the dollar strengthens against most other currencies. This creates directional trading opportunities that attract more participants to the market, increasing overall liquidity.
Conversely, when a central bank cuts rates or signals a dovish stance, capital tends to flow out of that currency. The currency weakens, and traders position accordingly.
The key point for brokerage operators is that interest rate divergence between countries is one of the primary reasons forex markets are as liquid as they are. Without these differentials, there would be far less reason for capital to move between currencies.
The Carry Trade: Where Interest Meets Liquidity in Practice
What Is the Tradeoff Between Interest and Liquidity – The carry trade is the most direct expression of the tradeoff between interest and liquidity in forex markets. A carry trade involves borrowing in a low-interest-rate currency and investing in a high-interest-rate currency, pocketing the difference as profit.
For example, if the Japanese yen has a near-zero interest rate and the Mexican peso offers 10%, a trader can sell JPY and buy MXN, earning the interest rate differential every day the position is held. This differential is reflected in the swap rate that your brokerage charges or pays on overnight positions.
Carry trades are enormously popular during periods of stable interest rate differentials and low volatility. They generate consistent returns and attract large volumes of institutional and retail capital. For your brokerage, carry trade activity means higher trading volumes, more overnight positions (which generate swap revenue), and increased client engagement.
However, carry trades are also a textbook example of the interest-liquidity tradeoff in action. The high-yielding currencies that attract carry trade capital, such as MXN, ZAR, TRY, or BRL, are typically less liquid than major currencies.
When market sentiment shifts and risk appetite drops, carry trade positions unwind rapidly. Traders rush to sell the high-yield currency and buy back the funding currency, and because exit liquidity in these pairs is thinner, the price moves can be extreme.
The Japanese yen carry trade unwind in August 2024 is a recent example. When the Bank of Japan unexpectedly raised rates, trillions of yen in carry trade positions unwound within days, causing sharp moves across multiple currency pairs and equity markets.
Brokers who offered high leverage on carry trade pairs without adequate risk controls faced significant client losses and margin call cascades.
Read More: Top 10 Largest Market Makers: Global Liquidity Leaders
Conclusion
What Is the Tradeoff Between Interest and Liquidity – Whether you are launching a new brokerage or optimizing an existing one, building your operations around a solid understanding of how interest and liquidity interact gives you a structural advantage over competitors who treat these as separate concerns.
Are you ready to launch a brokerage built on institutional-grade infrastructure? Start your own forex broker with Turnkey Inside and get access to our complete technology stack, including MT5 White Label, liquidity aggregation, CRM, payment solutions, and risk management.
Contact our team today and build a brokerage that thrives in any interest rate environment.
